By Stan Leconte

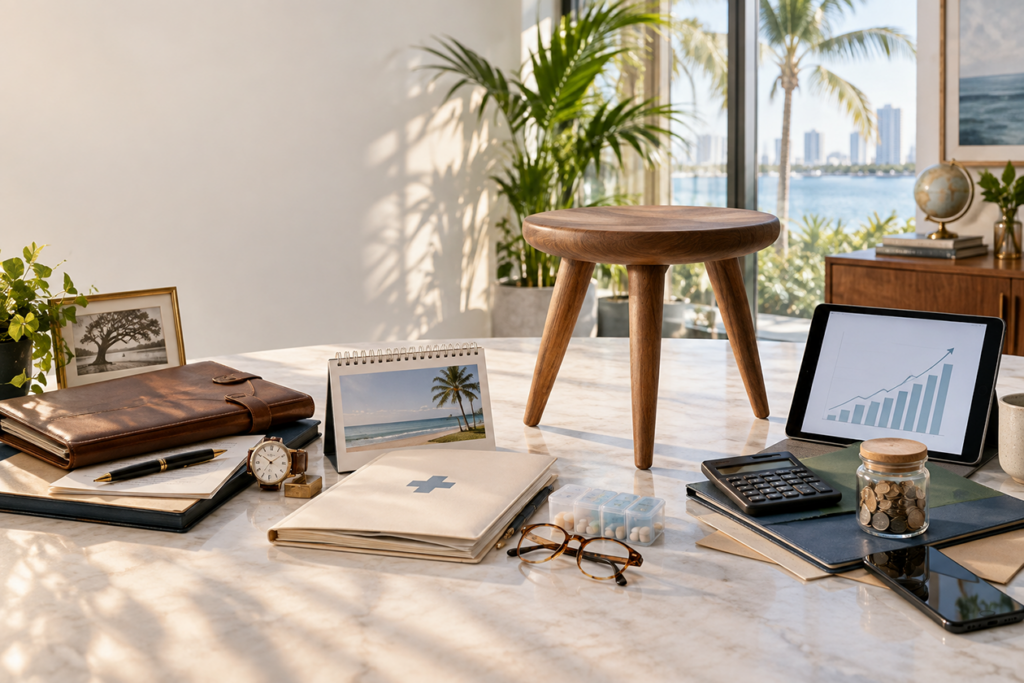
Earlier generations had a clearer retirement roadmap. They’d work, earn a pension, collect Social Security, save personally, and retire with dependable income. That’s what I’d call the traditional three legged stool, pension, Social Security, and savings, a shared responsibility among the employer, the government, and the worker.
Sounds secure, doesn’t it?
Today, that stool is wobbling.
Some public employees still have a strong first leg. Eligible members of the Florida Retirement System Pension Plan can receive monthly income for life. Qualified DROP participants can continue working while their pension benefits accumulate until they leave FRS employment.
Most private sector workers face a different reality. Only 14% had access to a traditional defined benefit plan in 2025. The pension has largely been replaced by the 401(k), shifting much of the responsibility and investment risk from the employer to the employee.
The second leg, Social Security, is also under pressure. In 2026, the average retired worker benefit is approximately $2,071 per month. The maximum for someone retiring at full retirement age is $4,152, although an individual’s actual benefit depends on earnings history and claiming age.
Social Security is not projected to disappear, but the warning is serious. The 2026 Trustees Report estimates that the retirement trust fund’s reserves could be depleted in late 2032. Without legislative action, continuing revenue would cover only an estimated 78% of scheduled retirement benefits.
That leaves the third leg, which is you and your ability to save.
Today’s worker must intentionally fund 401(k)s, Roth accounts, IRAs, bank savings, and brokerage accounts while understanding the different taxes, risks, and rules attached to each one.
According to the Federal Reserve, only 35% of nonretirees said their retirement savings were on track in 2025. In other words, nearly two out of every three working Americans did not believe they were on course.
Sobering, is it not?
Why? Because saving for tomorrow competes with surviving today: mortgages, rent, food, insurance, children, debt, and emergencies. Meanwhile, social media gurus promise instant wealth through the latest stock, cryptocurrency, real estate strategy, or side hustle.
But wealth is not built through magic or the gurus on social media. Money is a tool, and finance is a discipline. A personalized financial plan can help you navigate these choices, measure the gap, coordinate your accounts, and build a disciplined strategy for saving, investing, taxes, and retirement income.
The old system helped carry the worker. Today’s worker is increasingly expected to carry the system. The old three legged stool is barely standing, but unless we intentionally strengthen that third leg, many small businesses, entrepreneurs and wage earners may discover too late that two weakened legs cannot stand on their own.
“Someone is sitting in the shade today because someone planted a tree a long time ago.” Warren Buffett
Stan LeConte, CFP®, CRPC®, is the founder of IAA Private Wealth Advisors, an independent fiduciary wealth management firm based in Aventura. He holds both 2-15 and 2-20 licenses, owns a separate property and casualty insurance agency, and specializes in tax planning, estate planning, and investment strategy for high-net-worth individuals, professionals, and business owners.
