 By Robbie Bell
I owe a great deal of thanks to my accountant.
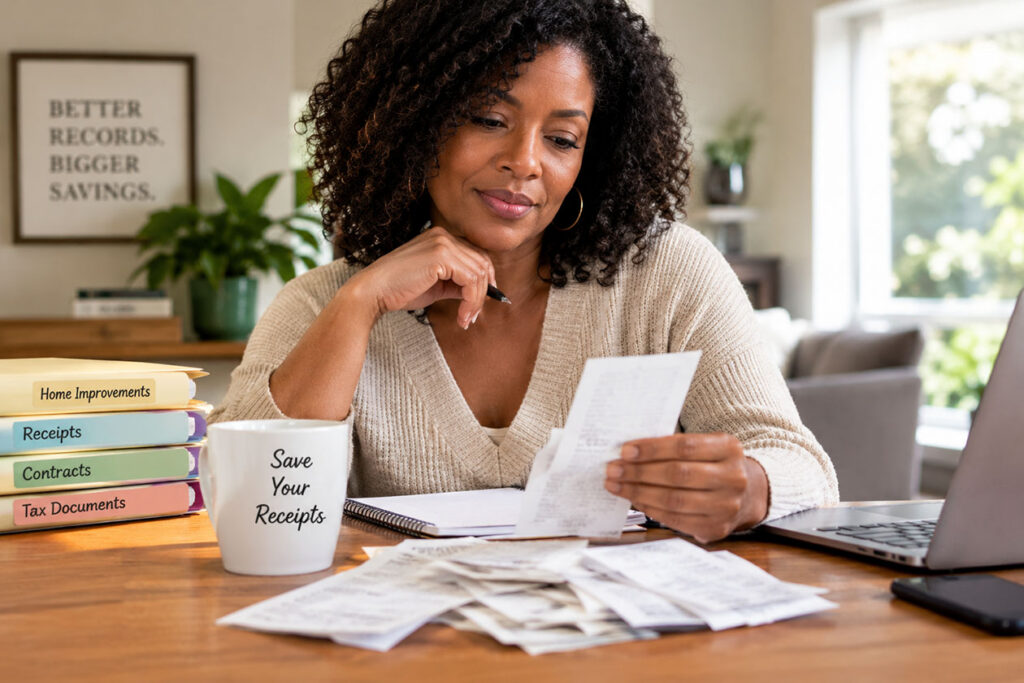
I sold my condo, and it was subject to a huge capital gains bill. I almost fainted when I saw how much. Then Gerri asked me a very important question: “Do you have any receipts?”
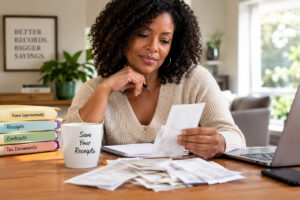
Do I have receipts??? Absolutely!
Gerri helped navigate a maze of taxes, but it’s not only about what she did—it’s also about what I did to save myself.
My accountant is Geraldine “Gerri” Lazarre, president of TriMerge Consulting Group, a full-service accounting and consulting firm.
I asked her about the importance of saving your receipts. She advised the following; these are her words:
One thing that is extremely important for property owners is keeping good records.
When you eventually sell a property, your capital gain generally isn’t determined simply by taking the selling price and subtracting what you originally paid. Certain improvements you’ve made to the property may increase your cost basis, which can reduce the amount of gain that is potentially subject to tax.
For example, if you purchased a property for $500,000 and over the years invested $150,000 in qualifying capital improvements, those documented improvements may increase your cost basis to $650,000. When the property is sold, that higher basis can make a significant difference in calculating the taxable gain.
This is why it’s so important to save invoices, receipts, contracts, proof of payment, permits, and other documentation for substantial work done.
And what about your primary residence?
There is an important federal tax provision that many homeowners have heard about, but it is important to understand that it does not automatically apply to every sale of real estate.
Under current federal tax law, a homeowner who qualifies may be able to exclude up to $250,000 of gain from the sale of a principal residence, or up to $500,000 for certain married couples filing a joint return.
Generally, to qualify for the full exclusion, the home must have been owned and used as your principal residence for at least two years during the five-year period ending on the date of the sale. There are additional requirements, limitations, and exceptions, including rules regarding how frequently the exclusion can be used.
And here is where those receipts can become especially important.
Even if you qualify for the principal residence exclusion, what happens if your gain is greater than the amount you are permitted to exclude? Properly documented qualifying improvements may increase your adjusted cost basis, which may reduce the amount of gain remaining after the exclusion that is potentially taxable.
The principal residence exclusion is also not a blanket exclusion for every property you own. Different tax rules can apply to second homes, vacation properties and rental or investment properties.
So, the key takeaway is simple: DON’T THROW AWAY THE RECEIPTS.
Robbie Bell, CIPS, ABR, SRES, CREPS, is your urban lifestyle real estate broker associate, licensed through Berkshire Hathaway HomeServices EWM Realty. Feel free to call Robbie at 305-528-8557 or write her at robbie@robbiebell.com with any questions you may have about selling or buying real estate.
